Starcloud Raises $250M for Orbital AI Data Centers
Starcloud raised $250M at a $2.3B valuation, with Nvidia joining, to build AI data centers in orbit. Why space compute is drawing capital now.

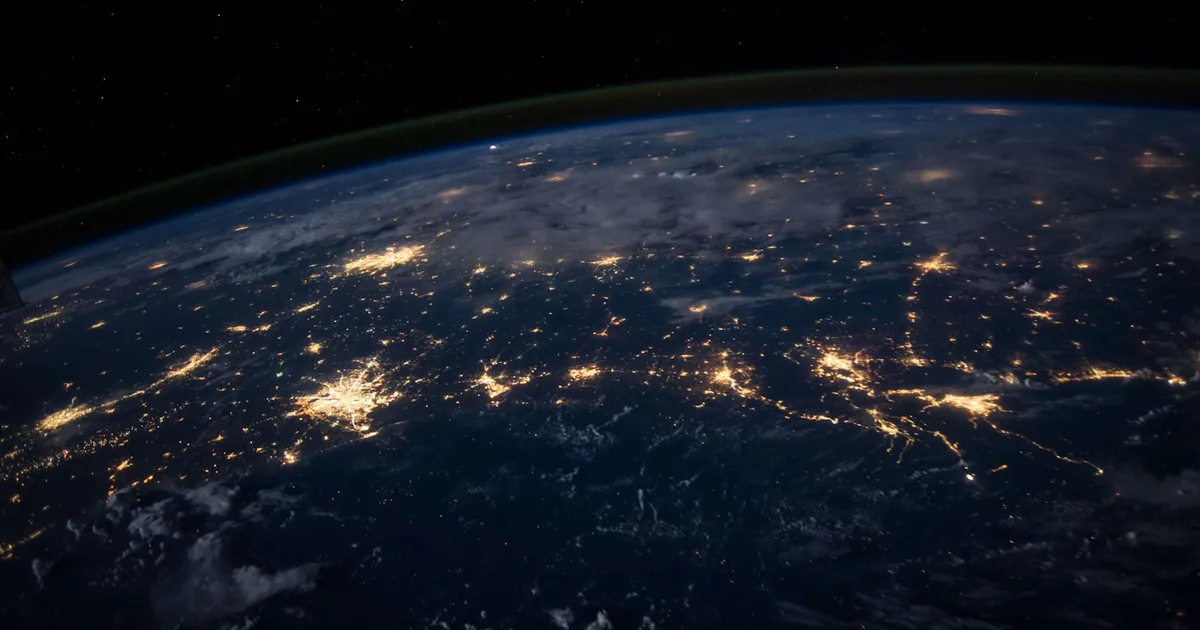
A startup betting that the next frontier for AI computing is literally above the planet has just doubled its valuation. On August 21, 2026, Starcloud, a Redmond, Washington company building data centers in orbit, said it raised $250 million in a Series A extension that values it at $2.3 billion — twice its prior mark. Notably, Nvidia joined the round as a new investor, lending the most valuable name in AI hardware to one of the more speculative ideas in AI infrastructure.
The financing brings Starcloud’s total capital raised since its 2024 founding to about $450 million. Investment firm Manhattan West led the extension, with participation from existing backers including Benchmark, EQT, Soma, NFX, and 776, alongside new investors Nvidia, Cisco Investments, Cedar Capital, Goanna Capital, and Standard Capital. A person familiar with the deal put Nvidia’s contribution at roughly $25 million — a small check for Nvidia, but a meaningful signal in a market with few active players.
What Starcloud is building
Starcloud’s premise is that the constraints throttling AI data-center growth on the ground — power, cooling, land, and grid access — can be addressed by moving compute into space. In orbit, solar power is abundant and nearly continuous, and the cold vacuum offers a radiative path for dissipating heat without the enormous water and electricity budgets that terrestrial data centers spend on cooling. The company’s plan is a constellation of orbital data centers: satellites carrying AI accelerators, networked together and powered by large solar arrays.
The new capital is earmarked for the unglamorous work of turning that vision into hardware — building manufacturing capacity, procuring rocket launches, and continuing engineering with Nvidia. The two companies have a working relationship that predates this round. Starcloud flew the first Nvidia H100 GPU to orbit aboard its Starcloud-1 satellite in November 2025, and they are now collaborating on Nvidia’s Space-1 Vera Rubin Module, a computing system Nvidia unveiled in March designed to bring more powerful AI processing to satellites. That connection ties Starcloud to Nvidia’s Rubin platform, the accelerator generation Nvidia is positioning as the backbone of next-wave AI compute.
For Nvidia, the investment is characteristically small and strategic. The company has spread modest stakes across a widening slice of the AI stack, from foundation-model labs to specialized infrastructure bets, using equity checks to seed demand for its chips in emerging markets. An orbital data-center company that designs around Nvidia silicon is, from that vantage, both a customer and an option on a market that may or may not exist at scale.
The case for compute in orbit
The bull case rests on a real and worsening problem. AI’s appetite for computing power is colliding with the physical limits of the electrical grid. Data centers are increasingly bottlenecked not by the availability of chips but by the availability of power — utilities in several regions have warned they cannot connect new large loads for years, and the capital-expenditure boom among hyperscalers is running ahead of the grid’s ability to supply it. When power, land, and cooling become the binding constraints, exotic alternatives start to look less far-fetched.
Space offers a genuinely different resource envelope. A satellite in the right orbit can bask in near-constant sunlight, sidestepping the intermittency that plagues terrestrial solar, and it can radiate heat into the vacuum rather than pumping it into scarce municipal water supplies. Proponents argue that as the economics of AI data centers tighten on the ground — with power and cooling costs climbing and permitting timelines stretching — the cost curve for orbital compute could eventually cross beneath the terrestrial one for certain workloads.
There is also a timing argument embedded in the round’s framing. Reporting on the raise noted that Starcloud is pressing ahead “as launch options dry up,” a reference to constrained access to rockets — which makes the company’s decision to spend fresh capital securing launch capacity now, ahead of competitors, a strategic hedge as much as an operational necessity.
The reasons for skepticism
For all the elegance of the pitch, orbital data centers remain far more concept than industry, and the obstacles are formidable. Launch costs, though falling, still make putting mass into orbit expensive, and data centers are heavy — racks of accelerators, power systems, and radiators are not lightweight payloads. Radiation in space degrades electronics and demands hardening that terrestrial chips do not need. Maintenance is effectively impossible in the way it is routine on the ground; a failed component in orbit cannot be swapped by a technician. And latency and bandwidth between orbit and terrestrial users constrain which workloads make sense up there in the first place — training runs that tolerate delay are more plausible candidates than latency-sensitive inference.
Then there is the gap between a demonstration and a business. Flying a single H100 to orbit in 2025 proved a GPU can operate in space; it did not prove that a networked constellation delivering competitive cost-per-computation is achievable, let alone economical. Starcloud’s own timeline reflects that distance — the company’s capacity ambitions are measured in years, not quarters, and the $250 million, while substantial for a startup, is a rounding error against the tens of billions that hyperscalers are pouring into terrestrial capacity every quarter.
The valuation doubling to $2.3 billion, on the back of a demonstration mission and a partnership rather than revenue at scale, also reflects the froth in AI infrastructure fundraising as much as Starcloud’s specific progress. Investors are paying up for exposure to any credible answer to the compute-supply crunch, and orbital data centers are a high-variance bet: potentially transformative if the physics and economics cooperate, potentially a cautionary tale if they do not.
Nvidia’s widening web of bets
The round fits a now-familiar pattern in which Nvidia’s capital shows up across the AI ecosystem, seeding demand for its accelerators wherever new compute might be built. The chipmaker has taken stakes and struck deals spanning model labs, infrastructure financiers, and specialized hardware ventures — from backstopping massive data-center financing for OpenAI to holding an equity position that surfaced in its $21 billion SpaceX stake disclosure. Each check is small relative to Nvidia’s balance sheet; in aggregate they describe a company methodically buying influence over the entire market that depends on its chips.
For Starcloud, Nvidia’s name carries weight beyond the $25 million. It validates the technical premise — Nvidia is not in the habit of designing space-rated computing modules for markets it thinks are fantasy — and it signals to other investors and potential customers that the orbital-compute thesis has at least one credible hardware partner. Whether that endorsement translates into a functioning industry is the open question the money is betting on.
What it means
Starcloud’s raise is a small financing with an outsized signal: capital is now flowing toward even the most speculative answers to AI’s compute-supply problem, and Nvidia is willing to seed them. The $250 million and the doubled valuation say less about orbital data centers being ready than about how acute the grid and power constraints on the ground have become — investors are pricing in a future where terrestrial compute cannot scale fast enough, and paying for optionality on alternatives.
Who wins. Starcloud gets the capital and the credibility to keep building, and its early backers see their stakes double on paper. Nvidia buys a cheap option on a potential new market for its silicon while reinforcing its Space-1 Rubin efforts. And the broader narrative that compute scarcity is real — not hype — gains another data point.
Who should stay skeptical. Anyone underwriting the economics. Launch costs, radiation, maintenance, and bandwidth remain unsolved at the scale a real data center requires, and a demonstration GPU in orbit is a long way from a competitive constellation. The valuation reflects AI-infrastructure froth as much as technical progress.
What to watch next. First, whether Starcloud can move from single-satellite demonstrations to a networked constellation that delivers usable, cost-competitive compute — the milestone that separates a science project from a business. Second, how far Nvidia’s Space-1 Vera Rubin Module actually gets, since Starcloud’s roadmap is tied to it. And third, whether the terrestrial power crunch that makes orbital compute attractive eases or worsens; the entire thesis depends on the ground staying constrained long enough for space to catch up.
Tagged
Keep reading
 Chisato · · 5 min read
Nvidia Australia AI Factories: 2 GW Buildout by 2027
Nvidia lined up eight Australian data center operators to build up to 2 GW of AI factory capacity by 2027, roughly doubling the nation's compute footprint.
 Chisato · · 6 min read
Anthropic Lambda $35B Deal: Texas Data Center, Nvidia Twist
Anthropic signed a six-year, $35B cloud deal with Nvidia-backed Lambda for 350MW at a Hut 8 site in Texas. Here's the structure and the circular-financing question.
Chisato · · 5 min read Anthropic Volta $10B Compute Deal: What to Know
Anthropic signed a $10B, six-year deal for 121MW of Nvidia Vera Rubin capacity at a Bitdeer data center in Norway, delivered by Volta. Here's the breakdown.